Automated Submissions
Submit deals without ever touching a portal
Every wrong match costs you a deal
The merchant takes the first acceptable offer. A decline you could have predicted hands the deal to whoever guessed better.
40%
of submissions go to the wrong lender
30+ min
per deal, checking ten lenders by hand
2–3 days
lost to every decline
Don’t build integrations. Send the deal.
Every lender takes submissions its own way. A portal, an API, an inbox. Keeping up with that is engineering work, and it is not what a broker is for.
One deal, ten different forms
Every lender wants the same information in its own order, in its own portal, with its own fields and upload rules.
Retyping is where offers die
A transposed revenue figure or a missing statement page comes back as a decline, or as an offer you have to walk back.
The first clean file wins
Merchants comparison-shop within hours. The lender who sees a complete submission first is usually the one who writes the deal.
Sydney Stewart
TFG Financial
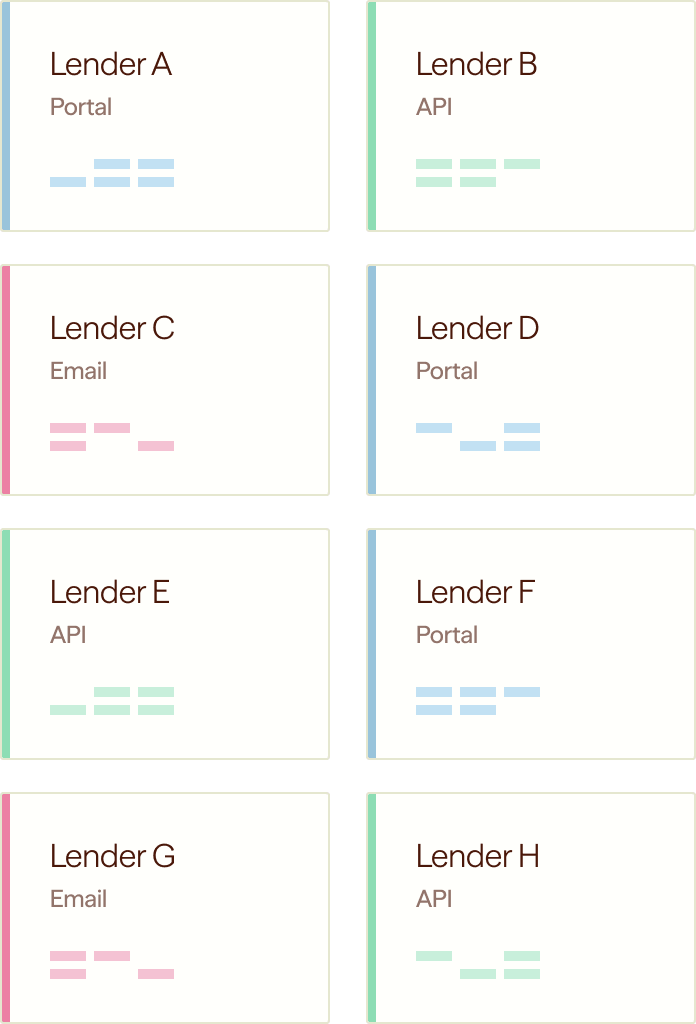
Every lender, the way they want it
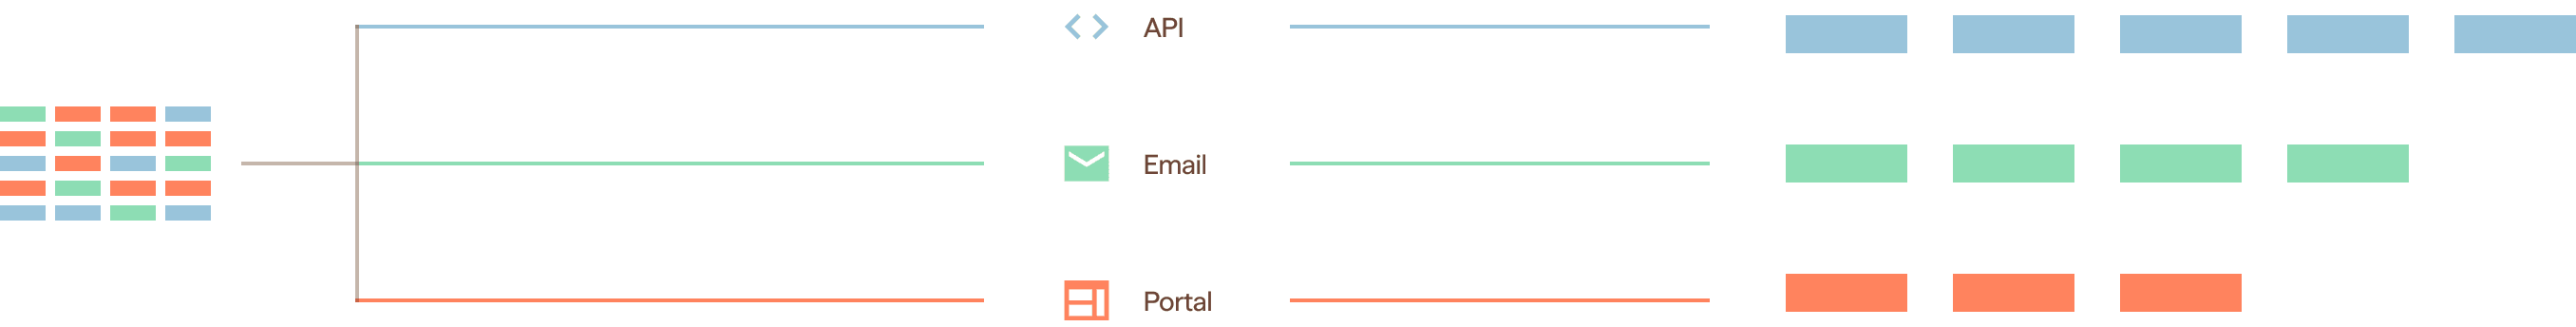
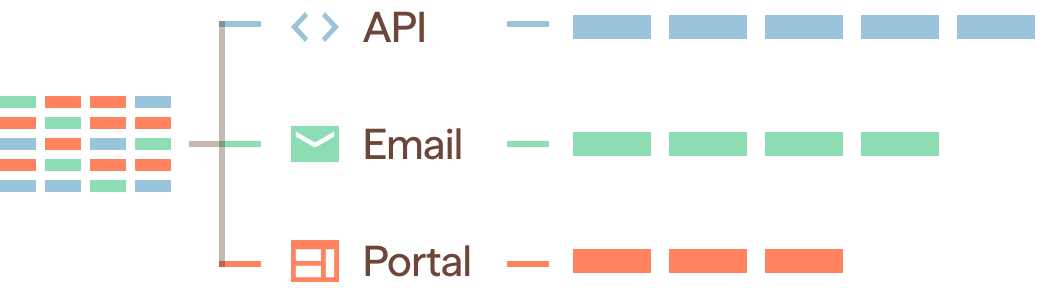
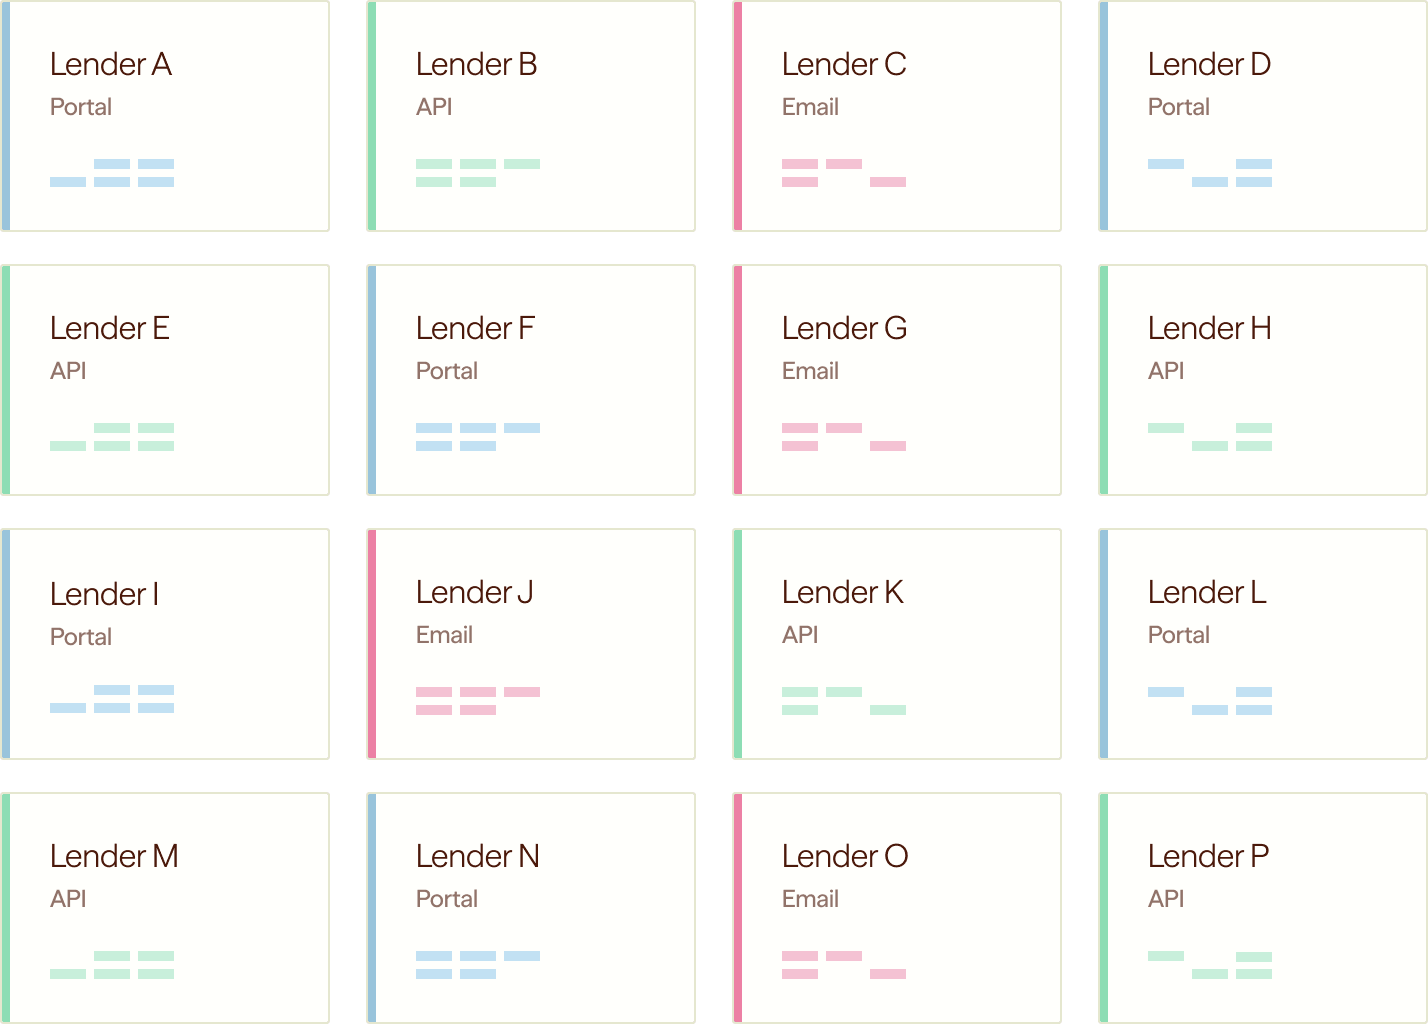
Set the channel once per lender. Heron formats and sends every submission the way that lender takes it.
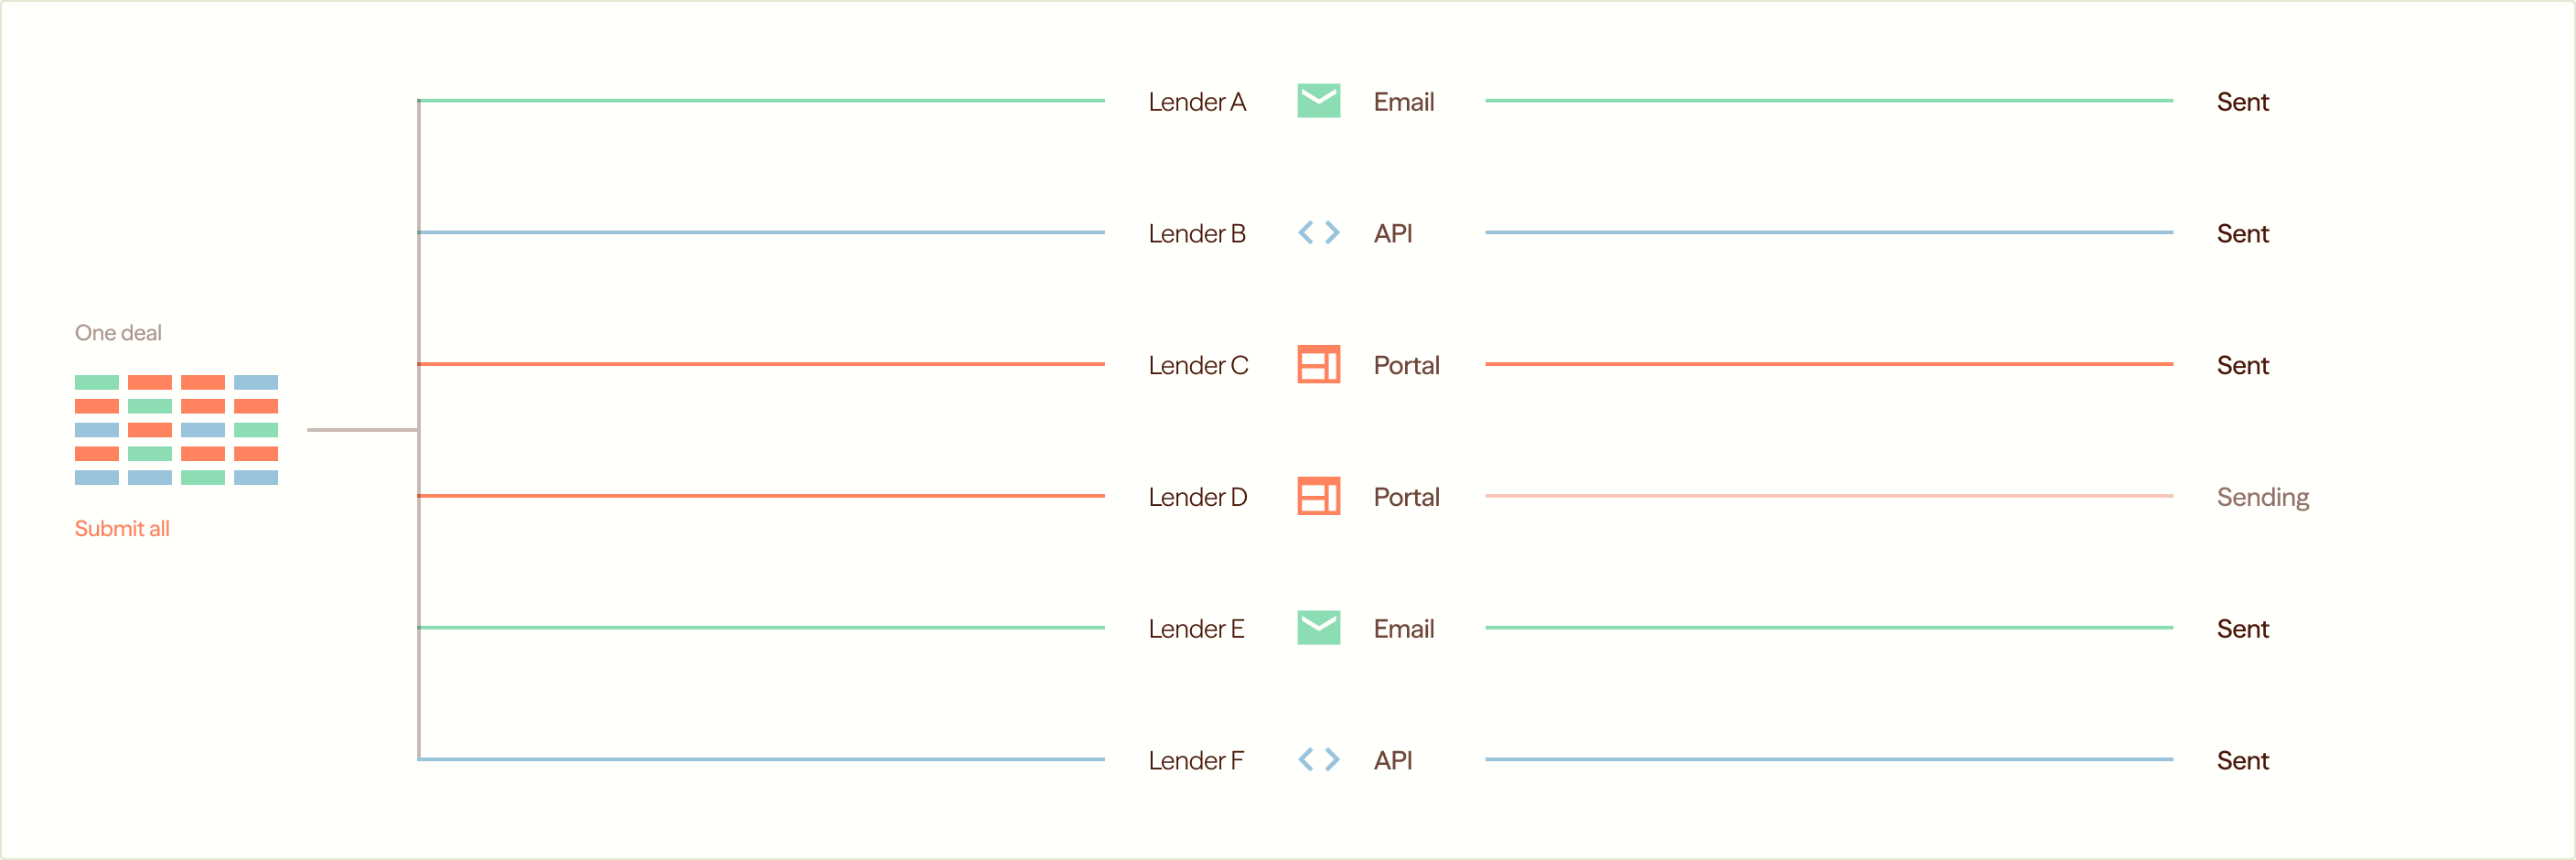
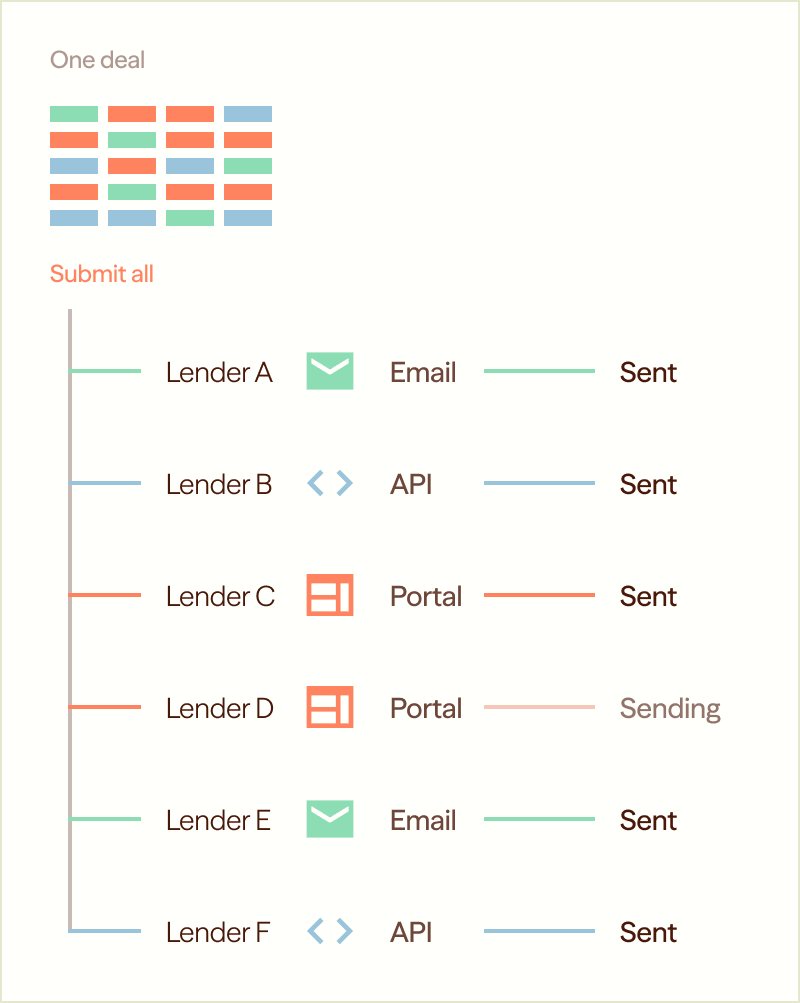
All six go out at once. Every integration is reusable — once Heron supports a lender, the next broker submitting to them goes live the same day.
Both funders and brokers run on Heron
Funders underwrite on Heron. Brokers submit on Heron. Your deal arrives complete, verified, and in the format the funder already trusts.
Purpose-built AI for SMB working capital
60K
submissions analyzed daily
15%
of US businesses seeking capital
Same day
a funder integration, reused by the next broker
Everything between the submission and the offer
The file lands, gets scrubbed, matched to the lenders that fit, submitted the way each one wants, and every answer comes back on the deal.
One path end to end, and you can start anywhere on it.
Bank Statement Scrubbing
Revenue, positions, NSFs and fraud flags off every statement, structured in seconds.
Lender Matching
Scored against every lender's credit box and your own partner preferences, then stacked best-first.
Automated Submissions
API, email or portal. Filled and sent the way each lender takes it, with no integration to build.
Decision Intake
Approvals, counters and declines pulled straight out of your inbox and filed against the right deal.
Heron saves a ton of time for our adjusters. These are highly analytical people, you want them using their brain for adjudication, not thinking about manually copying information.
We want this information on every deal...Heron is positioned at the top of our funnel because it's handling the most important data.
We're more consolidated and organised in the underwriting space now. And candidly — we're funding more deals.
We used to be online at 10 p.m. and work until 1 a.m. just entering applications. With Heron, we're finally out from behind the keyboard — we're meeting partners, traveling, growing the business. That just wasn't possible before.
An application comes in with bank statements. Nobody touches it. Heron automatically takes all that data, parses it, automatically sets up a contact record, an account record, and an opportunity in Salesforce. And then it automatically digitizes the statements.
We get an application emailed in, the statements go straight to Heron, and we do nothing else. Then the underwriter's got all the data they need to decide. It's the piece that kicks the whole process off...if you can't parse the bank info, you can't do anything else.
The OCR piece is obviously valuable, but everybody does that. What made us choose Heron was its ability to plug directly into our intake workflow, automate submission processing, and integrate deeply with our underwriting system.
Being able to automate bank statement scrubbing and structuring data allowed us to eliminate agents to about half of our total, and also to repurpose some agents in more verification roles, as opposed to doing this heavy manual lifting.
Heron is quite easily number one in importance for our tech stack...Realistically, you are not going to be able to put together an educated view of someone's account if you're only doing open banking-based underwriting.
By using Heron, I was able to eliminate our data processing function, which was 3 humans making $60-75K per year, that capped out at a total max output of 100 applications processed per day
With our growth, we would not have been able to handle the volume without Heron. I can triple my volume and not worry.
If we got a straight-through application... we could get a quote out the door in five minutes. Before, it was 24 hours.
With Heron, we went from 30% default ratio to 10.7%. That's ~$6 million per year saved in defaults for us.
If Heron goes down, our entire card approval decisioning system goes down.
That's what we like about Heron — they deliver a superior product. Faster, smarter, genuinely outstanding, and they blow their competition out the water.

Heron analyzes all of those historical records and evaluates fraud risk automatically within 5 seconds. Literally like 5 seconds.
Heron saves a ton of time for our adjusters. These are highly analytical people, you want them using their brain for adjudication, not thinking about manually copying information.
We want this information on every deal...Heron is positioned at the top of our funnel because it's handling the most important data.
We're more consolidated and organised in the underwriting space now. And candidly — we're funding more deals.
We used to be online at 10 p.m. and work until 1 a.m. just entering applications. With Heron, we're finally out from behind the keyboard — we're meeting partners, traveling, growing the business. That just wasn't possible before.
An application comes in with bank statements. Nobody touches it. Heron automatically takes all that data, parses it, automatically sets up a contact record, an account record, and an opportunity in Salesforce. And then it automatically digitizes the statements.
We get an application emailed in, the statements go straight to Heron, and we do nothing else. Then the underwriter's got all the data they need to decide. It's the piece that kicks the whole process off...if you can't parse the bank info, you can't do anything else.
The OCR piece is obviously valuable, but everybody does that. What made us choose Heron was its ability to plug directly into our intake workflow, automate submission processing, and integrate deeply with our underwriting system.
Being able to automate bank statement scrubbing and structuring data allowed us to eliminate agents to about half of our total, and also to repurpose some agents in more verification roles, as opposed to doing this heavy manual lifting.
Heron is quite easily number one in importance for our tech stack...Realistically, you are not going to be able to put together an educated view of someone's account if you're only doing open banking-based underwriting.
By using Heron, I was able to eliminate our data processing function, which was 3 humans making $60-75K per year, that capped out at a total max output of 100 applications processed per day
With our growth, we would not have been able to handle the volume without Heron. I can triple my volume and not worry.
If we got a straight-through application... we could get a quote out the door in five minutes. Before, it was 24 hours.
With Heron, we went from 30% default ratio to 10.7%. That's ~$6 million per year saved in defaults for us.
If Heron goes down, our entire card approval decisioning system goes down.
That's what we like about Heron — they deliver a superior product. Faster, smarter, genuinely outstanding, and they blow their competition out the water.
Heron analyzes all of those historical records and evaluates fraud risk automatically within 5 seconds. Literally like 5 seconds.